When managing your finances, understanding your credit score is one of the most important steps toward making better borrowing decisions. Whether you are applying for a credit card, purchasing a car, taking out a personal loan, or planning to buy a home, your credit score can influence your financial opportunities. However, many people become confused when they see different numbers on banking applications, credit monitoring websites, and loan documents.
One common question consumers ask is: is FICO score same as credit score?
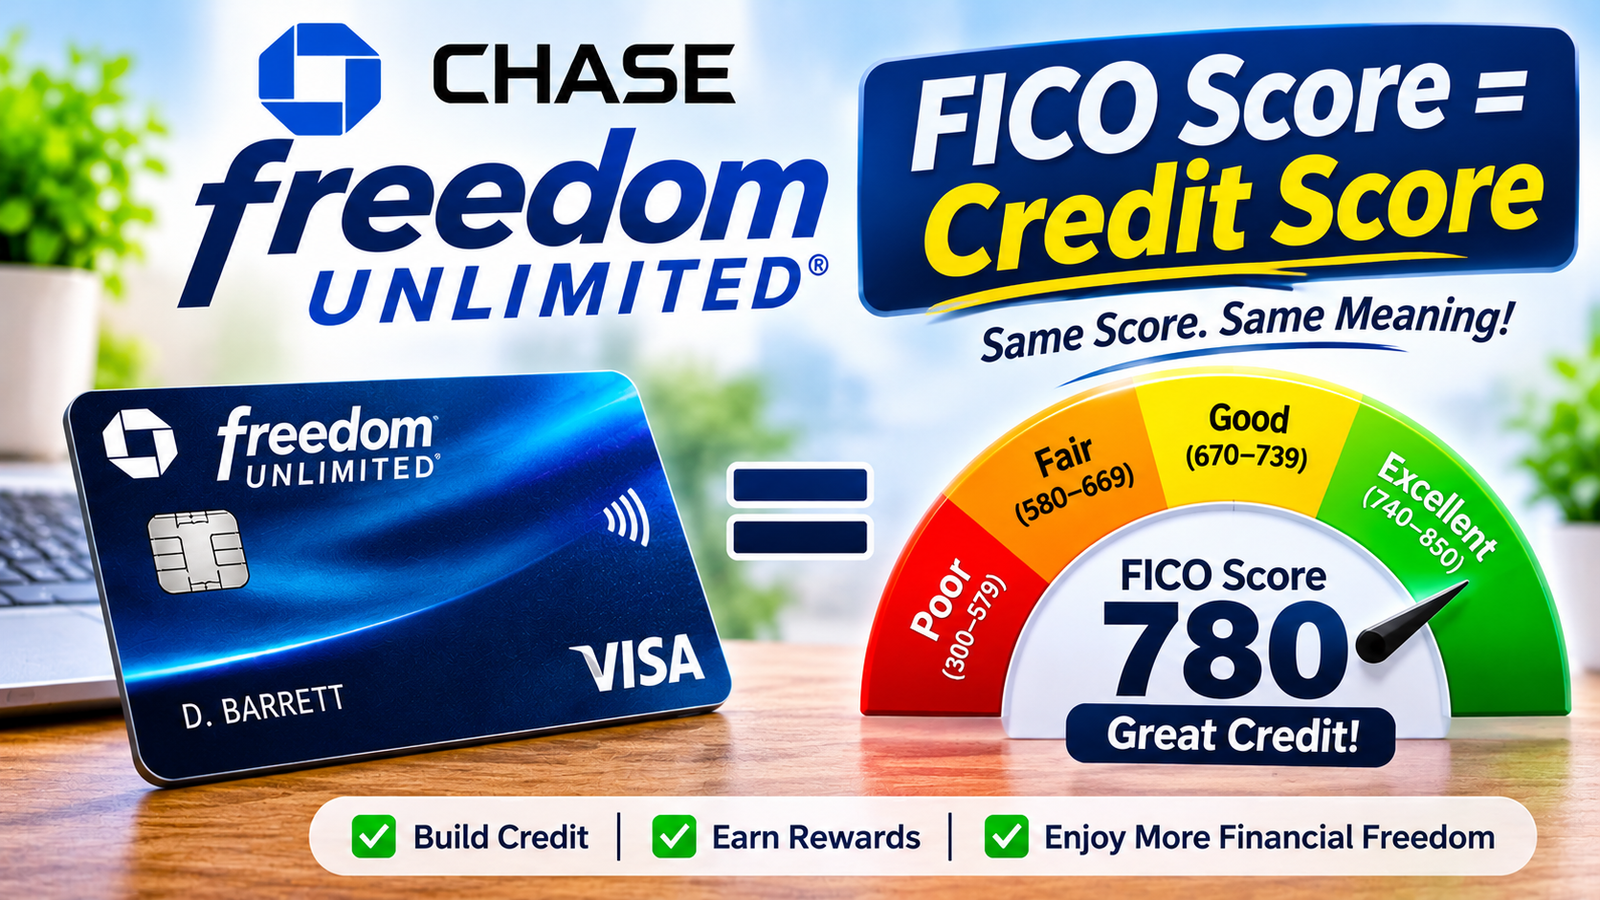
The simple answer is no. A FICO Score is a particular type of credit score developed by Fair Isaac Corporation, while a credit score is a general term used to describe different systems that evaluate a person’s creditworthiness.
Although both are used to estimate how responsibly someone manages borrowed money, they are not always calculated in the same way. Different scoring companies use different formulas, versions, and credit information, which can result in different numbers for the same individual.
Understanding how these systems work can help you monitor your financial health, prepare for loan applications, and avoid confusion when checking your credit information. Let’s explore the differences, scoring ranges, calculation methods, and practical ways to maintain a healthy credit profile.
What Is a FICO Score?
A FICO Score is a three-digit credit score developed by Fair Isaac Corporation. It helps lenders estimate how likely a person is to repay borrowed money based on their credit history.
FICO Scores are widely used throughout the United States by banks, credit card companies, mortgage providers, and automobile lenders. These scores help financial institutions evaluate lending risk when reviewing applications.
Most standard base FICO Scores range from 300 to 850. Generally, a higher score indicates a stronger credit profile and a lower estimated risk of missing payments.
FICO calculates scores using information collected from credit reports maintained by three major credit reporting agencies:
- Experian
- Equifax
- TransUnion
These credit bureaus collect information about your borrowing and repayment activities. FICO uses relevant details from these reports to calculate scores through its proprietary mathematical models.
A FICO Score may influence several financial decisions, including:
- Approval for credit cards and personal loans.
- Interest rates offered by lenders.
- Mortgage qualification.
- Automobile financing terms.
- Credit limits and borrowing opportunities.
However, having a strong FICO Score does not guarantee loan approval. Lenders may also consider income, employment, existing debt, and other financial circumstances.
What Is a Credit Score?
A credit score is a numerical representation of your creditworthiness. It gives lenders an idea of how responsibly you have managed financial obligations in the past.
Credit scoring models analyze information from your credit reports and convert it into a number. This makes it easier for lenders to evaluate applicants using consistent risk assessment methods.
Your credit score can be influenced by several financial activities, including:
- Paying credit card bills on time.
- Managing outstanding loan balances.
- Maintaining older credit accounts.
- Applying for new credit.
- Using available credit responsibly.
- Managing different types of borrowing.
A credit score is not a permanent number. It can change as new information appears on your credit reports.
For example, if you pay down a large credit card balance, your credit utilization may decrease. Depending on when your lender reports the updated balance and which scoring model is used, this change may help improve your score.
Similarly, a missed payment or newly reported collection account may negatively affect your credit profile.
There are several credit scoring systems available, including FICO and VantageScore. Each system has its own calculation methods and requirements.
What Is the Difference Between FICO Score and Credit Score?
The biggest difference is that FICO is a specific credit scoring system, whereas credit score is a general term that includes multiple scoring systems.
Both help lenders assess financial risk, but their calculations and results may differ.
Here is a closer comparison:
| Feature | FICO Score | Credit Score |
| Meaning | Specific credit scoring model | General term for credit scoring numbers |
| Developer | Fair Isaac Corporation | Different scoring companies |
| Common range | 300–850 for standard base models | Depends on the model |
| Calculation | Proprietary FICO formulas | Varies by scoring provider |
| Main purpose | Evaluate lending risk | Measure creditworthiness |
| Examples | FICO Score 8 and FICO Score 9 | FICO and VantageScore |
| Lender usage | Widely used by lenders | Depends on the scoring model |
Different Scoring Companies
FICO Scores are developed by Fair Isaac Corporation. VantageScore is another major credit scoring system developed jointly by Equifax, Experian, and TransUnion.
These companies use different mathematical approaches to evaluate credit information. As a result, your FICO Score and VantageScore may not match.
Different Calculation Methods
Credit scoring companies consider similar financial behaviors, but they do not necessarily assign the same importance to every factor.
For example, different models may evaluate credit history, recent account activity, and collection information differently.
Different Scoring Versions
FICO offers several scoring versions designed for different lending situations. A lender evaluating an automobile loan may use a different FICO model from a credit card company.
Therefore, you may have multiple FICO Scores at the same time.
Understanding FICO Score Ranges
Knowing your FICO Score range can help you understand how lenders may view your credit profile.
The standard base FICO scoring system generally uses a range from 300 to 850.
The following categories provide a general explanation of different score levels.
| FICO Score | Rating | General Description |
| Below 580 | Poor | Higher estimated lending risk |
| 580–669 | Fair | Below-average credit profile |
| 670–739 | Good | Generally acceptable credit profile |
| 740–799 | Very Good | Strong credit profile |
| 800–850 | Exceptional | Excellent credit profile |
These categories are general guidelines. Individual lenders may use different requirements when evaluating loan applications.
Poor Credit: Below 580
A score below 580 generally indicates a weaker credit history. Consumers in this category may find it difficult to qualify for certain financial products.
Possible challenges include:
- Higher interest rates.
- Limited credit card choices.
- More restrictive loan conditions.
- Additional application requirements.
However, a low score does not mean that improving your credit is impossible. Consistent payments, responsible borrowing, and correcting inaccurate credit information can help rebuild your financial profile.
Fair Credit: 580–669
Fair credit indicates that a consumer may have some positive borrowing history but also certain risk factors.
Late payments, high credit card balances, or a relatively short credit history may contribute to this category.
Reducing outstanding balances and making every payment on time can help strengthen your credit profile.
Good Credit: 670–739
A score within this range is generally considered good.
Consumers may qualify for a wider selection of financial products, although interest rates and approval decisions still depend on the lender and the complete application.
Very Good Credit: 740–799
Very good credit generally indicates responsible borrowing habits and a relatively strong repayment history.
Consumers in this range may have access to competitive interest rates and attractive credit products.
Exceptional Credit: 800–850
An exceptional FICO Score generally reflects a strong record of credit management.
People in this category often have established credit histories, consistent payments, and relatively low revolving credit balances.
Even with an exceptional score, lenders may still evaluate income, debt obligations, and other financial information.
How Is a FICO Score Calculated?
FICO Scores are calculated using several categories of information from your credit reports.
The standard FICO scoring framework considers five major factors. Each factor contributes differently to the final score.
1. Payment History: 35%
Payment history is generally the most influential factor in a standard FICO Score.
It examines whether you have paid your financial obligations on time.
Information may include:
- Credit card payments.
- Mortgage payments.
- Auto loan payments.
- Personal loan payments.
- Past-due accounts.
- Accounts sent to collections.
A consistent history of timely payments generally supports a stronger credit profile.
Even one late payment can negatively affect your score, depending on how late it is and the rest of your credit history.
The best approach is to pay your bills before their due dates. Automatic payments and calendar reminders can help prevent missed payments.
2. Amounts Owed: 30%
The amounts owed category evaluates how much debt you currently have.
One important part of this category is credit utilization, which measures how much of your available revolving credit you are using.
For example, suppose your credit card has a $10,000 limit and your outstanding balance is $2,000.
Your credit utilization would be:
Credit Utilization = (Outstanding Balance ÷ Total Credit Limit) × 100
In this example, your utilization rate is 20%.
Generally, lower credit utilization is better for your credit profile. Paying down credit card balances can help reduce the percentage of available credit you are using.
3. Length of Credit History: 15%
This factor considers how long you have been using credit.
It may include:
- The age of your oldest credit account.
- The age of your newest account.
- The average age of your credit accounts.
A longer history of responsible borrowing can demonstrate experience managing financial obligations.
This is one reason why closing an older credit card without considering the consequences may not be the best decision.
4. New Credit: 10%
Opening several new accounts within a short period may affect your credit score.
FICO considers recent credit inquiries and newly opened accounts when evaluating credit risk.
A hard inquiry generally occurs when a lender checks your credit after you apply for a financial product.
Although a single hard inquiry usually has a relatively small impact, multiple applications within a short period may create unnecessary pressure on your credit profile.
Apply for new credit only when you genuinely need it.
5. Credit Mix: 10%
Credit mix refers to the different types of credit accounts you manage.
Examples include:
- Credit cards.
- Personal loans.
- Mortgage loans.
- Automobile loans.
- Student loans.
Managing different types of credit responsibly may contribute positively to your score.
However, taking out unnecessary loans simply to improve your credit mix is not recommended.
Why Are My FICO Score and Credit Score Different?
Many consumers notice that their credit score changes depending on which financial website or banking application they use.
This is normal because credit scoring systems do not always use identical formulas or information.
Different Scoring Models
FICO and VantageScore use separate mathematical formulas.
Both evaluate credit-related information, but their methods can produce different results.
For example, one service may display a score of 720, while another shows 735.
This does not automatically mean that one service has made a mistake.
Different Credit Bureau Reports
Experian, Equifax, and TransUnion maintain separate credit reports.
Not every lender reports account information to all three bureaus. Therefore, your reports may contain slightly different details.
If one bureau receives an updated credit card balance while another has not yet received it, your calculated scores may differ.
Different Reporting Dates
Credit information is not always updated simultaneously.
A lender may report your latest payment or outstanding balance at one time, while another service may calculate your score using older information.
Consequently, scores can vary depending on when the calculation takes place.
Different FICO Versions
FICO has introduced multiple scoring versions over time.
Examples include:
- FICO Score 8.
- FICO Score 9.
- FICO Score 10.
- FICO Score 10T.
- Industry-specific FICO Scores.
These versions may evaluate certain credit information differently.
For example, automobile lenders and credit card companies may use industry-specific scoring models rather than a standard base FICO Score.
FICO Score 8 vs. VantageScore: Which Is Different?
FICO Score 8 and VantageScore are two credit scoring systems commonly encountered by American consumers.
Both are designed to estimate credit risk, but they have different developers and calculation methods.
| Feature | FICO Score 8 | VantageScore |
| Developer | Fair Isaac Corporation | Equifax, Experian, TransUnion |
| Common scoring range | 300–850 | 300–850 |
| Calculation method | FICO scoring formula | VantageScore formula |
| Main purpose | Evaluate credit risk | Evaluate credit risk |
| Available versions | Multiple | Multiple |
| Lender usage | Widely used | Also used by lenders |
One important difference involves how these systems evaluate credit history and certain account activities.
For example, VantageScore 3.0 and 4.0 may generate scores for some consumers with relatively limited credit histories, while FICO has its own minimum requirements for generating a score.
FICO Score 8 is widely used by lenders, but other versions may be more relevant for particular financial products.
Neither scoring system is automatically better for every situation. The most important thing is understanding which score your prospective lender uses.
How to Check Your FICO Score
Checking your FICO Score regularly can help you understand your credit position and identify changes that may need attention.
There are several ways to access your score.
1. Check With Your Bank or Credit Card Provider
Some U.S. banks and credit card companies offer free credit score information through their online banking applications.
However, check whether the displayed number is a FICO Score or a VantageScore.
Financial institutions do not all provide the same scoring model.
2. Use the Official myFICO Website
The myFICO website provides access to FICO Scores and educational resources.
Depending on the subscription or service selected, you may be able to review different FICO versions and credit bureau information.
Some services are paid, so review the available plans before purchasing.
3. Review Your Credit Reports
Consumers can access free credit reports from Experian, Equifax, and TransUnion through AnnualCreditReport.com.
Remember that checking a credit report is different from checking a credit score.
Your report contains detailed account information, while your score is calculated using information from that report.
Reviewing your reports can help you identify:
- Unrecognized credit accounts.
- Incorrect payment statuses.
- Inaccurate account balances.
- Duplicate collection information.
- Incorrect personal details.
If you identify an error, you can dispute it with the relevant credit bureau and the company that provided the information.
Practical Ways to Improve Your FICO Score
Improving your credit score requires consistent financial habits. There is no guaranteed shortcut that works for everyone, but several strategies can help strengthen your credit profile.
Pay Your Bills on Time
Payment history is the most influential category in standard FICO Scores.
Make sure your credit card and loan payments are made before their due dates.
Setting up automatic payments can help prevent accidental late payments.
Keep Credit Card Balances Low
High credit card balances can increase your credit utilization ratio.
For example, if your credit limit is $5,000 and your balance is $2,500, your utilization is 50%.
Reducing that balance can lower utilization and may help improve your credit profile once the updated information is reported.
Avoid Unnecessary Credit Applications
Applying for multiple credit cards or loans within a short period may result in several hard inquiries.
Before applying, research the product and understand its eligibility requirements.
Check Your Credit Reports for Errors
Incorrect information can negatively affect your credit profile.
Review your reports regularly and dispute information that is inaccurate or incomplete.
Maintain Older Credit Accounts Responsibly
Older accounts can contribute to the length of your credit history.
Before closing an account, consider its annual fees, available credit, and possible effects on your credit utilization.
Build a Consistent Credit History
If you are new to borrowing, focus on establishing a positive payment record.
You may consider a secured credit card or another suitable credit-building product if you meet its requirements.
The goal should be to develop responsible borrowing habits rather than accumulate unnecessary debt.
Does Your FICO Score Affect Loan Approval?
Yes. Your FICO Score can influence loan approval, interest rates, and borrowing conditions.
However, lenders generally consider more than just your credit score.
For example, when evaluating an automobile loan, a lender may examine:
- Your credit history.
- Monthly income.
- Existing financial obligations.
- Employment information.
- Requested loan amount.
- Loan repayment period.
A stronger credit profile may help you qualify for more competitive financing terms.
Consider two individuals applying for the same $25,000 automobile loan. One applicant has a long history of timely payments and low credit card balances, while the other has several missed payments and high outstanding debt.
The lender may consider the first applicant less risky and offer more favorable financing terms.
However, the actual decision depends on the lender’s policies and the complete financial application.
Before applying, ask which credit scoring model the lender uses. This can help you understand why the score displayed by your credit monitoring service may differ from the number used during the lending process.
Conclusion
Understanding the difference between a FICO Score and a credit score can help you make more informed financial decisions. Although the terms are closely connected, they do not mean exactly the same thing. A FICO Score is a specific scoring model developed by Fair Isaac Corporation, while a credit score is a general term that includes several systems used to evaluate creditworthiness.
Your FICO Score may differ from other credit scores because of different calculation methods, credit bureau information, reporting dates, and scoring versions. These differences are normal and do not necessarily indicate a problem with your credit history.
If you want to maintain a strong credit profile, focus on paying bills on time, keeping credit card balances low, limiting unnecessary credit applications, and reviewing your credit reports for errors. Most importantly, remember that responsible financial habits and consistent repayment behavior are the foundation of a healthy credit history.
Frequently Asked Questions (FAQs)
1. Is a FICO Score the same as a credit score?
No. A FICO Score is one specific type of credit score developed by Fair Isaac Corporation. Credit score is a broader term that includes different scoring models, such as FICO and VantageScore. Both help lenders evaluate how responsibly consumers manage borrowed money.
2. Which is better, FICO Score or credit score?
Neither is automatically better. FICO is a widely used scoring system, while credit score describes different ways of measuring creditworthiness. The most relevant score depends on the scoring model your lender uses when reviewing your application.
3. Why is my FICO Score different from my credit score?
Your scores may differ because different scoring models use different formulas, credit bureaus may maintain different information, and scoring services may update information at different times. These differences are common among consumers.
4. What is considered a good FICO Score?
A FICO Score between 670 and 739 is generally considered good. A score between 740 and 799 is very good, while scores from 800 to 850 are considered exceptional under the general FICO scoring categories.
5. Does checking my FICO Score lower it?
No. Checking your own FICO Score generally creates a soft inquiry, which does not lower your credit score. However, applying for a new credit card or loan may result in a hard inquiry that can temporarily affect your score.
1 Comment
[…] Read More: Is FICO Score the Same as Credit Score? Understanding the Differences […]